Experiencing a 10% spike in your health insurance cost can throw any household budget into disarray. Driven by rising medical inflation, prescription drug price increases, and subtle shifts in coverage policies, policyholders across the country are suddenly facing unprecedented monthly premiums and unexpected out-of-pocket expenses. Fortunately, navigating the Affordable Care Act (ACA) Marketplace does not have to mean accepting lower quality care or paying exorbitant rates.
By uncovering hidden fee structures, leveraging Premium Tax Credits, and choosing the right metal tier, everyday consumers are taking control of their medical finances. This detailed breakdown reveals why costs are soaring and provides actionable strategies to protect your family budget from hidden health fees.
The sudden 10% surge in monthly medical obligations represents a direct financial threat to working families, but taking immediate control through strategic plan restructuring is the single most effective defense against predatory rate inflation. Unchecked premium inflation combined with hidden deductibles rapidly erodes household savings if left unaddressed. Rather than passively accepting annual rate hikes, policyholders must audit their policy terms, recalibrate tax credit filings, and utilize specialized health spending accounts to insulate their monthly finances.
Uncovering the Root Causes Behind Soaring Health Insurance Cost and Hidden Fee Risks
Medical Inflation and Dynamic Marketplace Policy Shift Dynamics
Healthcare price inflation continues to outpace general economic indices, directly driving up the average baseline health insurance cost for individual policyholders. Hospital systems face escalated operational expenditures, labor shortages, and rising supply chain expenses, which insurers offset by inflating annual consumer premiums. Furthermore, advanced therapeutic treatments and specialty pharmaceuticals enter the consumer market at premium price points. These combined financial pressures force insurance carriers to recalculate actuarial risk models, resulting in steep rate spikes across both individual and family coverage tiers.
Policy adjustments within the Affordable Care Act Marketplace further alter baseline pricing structures each calendar year. Legislative updates affect federal subsidy thresholds, changing the net premium balance that households must pay out of pocket. As government contribution formulas fluctuate, middle-class consumers often experience sudden shifts in net monthly obligations. Understanding how federal subsidy calculations interact with state exchange pricing models allows policyholders to anticipate policy modifications before open enrollment windows close.
Unmasking Stealth Financial Trapdoors Hidden Within Policy Fine Print
Beyond rising monthly obligations, policyholders frequently encounter hidden structural fees that inflate overall health insurance cost burdens unexpectedly. Insurance carriers quietly adjust annual deductible amounts and modify co-insurance percentages within renewed contract terms. A plan featuring a stable monthly premium may quietly double its individual deductible, forcing families to shoulder thousands of dollars in medical costs before primary insurance benefits initiate during unforeseen medical emergencies.
Out-of-network service traps present another severe threat to family financial stability. Even when choosing an in-network hospital facility, individual attending physicians, radiologists, or anesthesiologists may operate under separate independent billing entities outside your insurer’s network. These surprise billing scenarios generate substantial balance bills that bypass standard coverage caps. Identifying network limitations early helps prevent catastrophic out-of-pocket liabilities resulting from ancillary medical service providers.
Navigating the complexities of modern medical coverage requires consistent vigilance and informed decision-making. By taking control of your policy options, auditing hidden fee structures, and leveraging tax-advantaged savings accounts, you can successfully protect your family budget from an unpredictable health insurance cost environment.
Ri
Evaluating Core Structural Factors Directly Dictating Health Insurance Cost Metrics
Navigating Metal Plan Categories on the ACA Exchange Market
Selecting an appropriate Marketplace metal tier plays a pivotal role in managing your long-term health insurance cost exposure. Bronze and Silver plans offer lower monthly premiums but require significantly higher deductibles and co-payments when receiving active medical treatment. Conversely, Gold and Platinum plans demand substantial monthly financial commitments while offering robust coverage that minimizes point-of-service expenses during routine doctor visits or complex medical procedures.
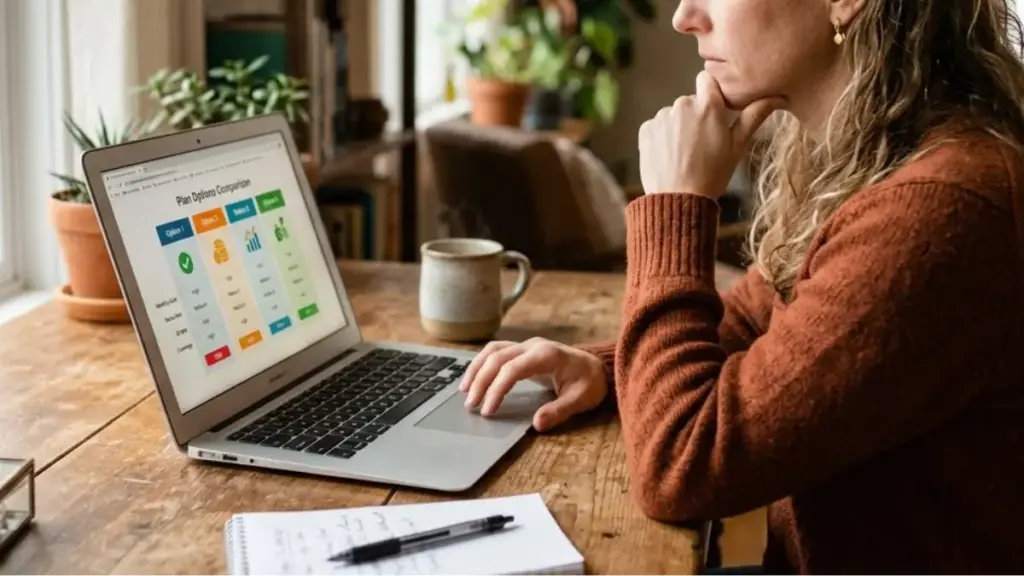
Misaligning metal tiers with actual household medical usage frequently leads to severe annual budget waste. Healthy individuals who rarely visit healthcare providers often overpay by selecting high-premium Gold plans, absorbing unnecessary monthly expenses. Conversely, individuals managing chronic conditions who opt for Bronze coverage often face overwhelming out-of-pocket costs due to massive deductibles. Balancing recurring monthly premiums against anticipated healthcare utilization ensures optimal financial efficiency across the entire coverage year.
Structural Impacts of Medical Network Tiers and Pharmacy Formularies
Insurance providers increasingly rely on narrow network structures to keep baseline health insurance cost rates competitive. These restricted networks limit policyholder access to specific regional hospital systems and medical groups, penalizing patients who seek care outside designated provider circles. While narrow networks lower monthly financial overhead, they restrict patient choice and increase the likelihood of accidental out-of-network service utilization during medical emergencies.
Prescription drug formularies represent another dynamic variable impacting total healthcare expenditures. Insurers frequently reclassify brand-name and specialty medications into higher pricing tiers, shifting substantial drug expenses directly onto consumers. A drug covered under a modest copay last year might suddenly require 50% co-insurance under a revised formulary schedule. Auditing annual medication lists against updated insurer formularies prevents costly surprises at the pharmacy counter.
Read more: Crucial Hospital Hygiene Standards Every Inpatient Needs to Inspect
Strategic Marketplace Frameworks to Optimize Coverage and Curb Expenditures
Harnessing Premium Tax Credits and Household Income Projections
Maximizing the ACA Premium Tax Credit (PTC) is the most direct method to suppress your net health insurance cost on the federal exchange. These sliding-scale subsidies lower monthly premium payments based on estimated annual modified adjusted gross income (MAGI). Accurately forecasting household earnings ensures families receive maximum financial assistance while avoiding costly tax reconciliation penalties at year-end.
[ruby_related heading=”More Read” total=5 layout=1 offset=5]
Updating life changes and income fluctuations on the Marketplace portal throughout the year protects household liquidity. A reduction in working hours, sudden career transitions, or changes in family size directly alter subsidy eligibility metrics. Promptly reporting income updates adjusts your subsidy allocation in real time, preventing sudden premium jumps or unexpected tax repayment liabilities during annual tax filing cycles.
Utilizing Health Savings Accounts and Flexible Spending Structures
Pairing a High Deductible Health Plan (HDHP) with a Health Savings Account (HSA) provides a powerful triple-tax advantage that mitigates your overall health insurance cost burden. HSA contributions are tax-deductible, grow tax-free, and remain tax-exempt when withdrawn for qualified medical expenses. This dedicated savings vessel enables policyholders to cover deductible obligations using pre-tax dollars, reducing net out-of-pocket healthcare expenses.
Flexible Spending Accounts (FSAs) offer a complementary avenue for managing predictable medical expenses within a single plan year. Unlike HSAs, FSA funds are subject to use-it-or-lose-it restrictions, requiring precise annual budgeting for prescriptions, dental treatments, and vision care. Combining tax-advantaged accounts with disciplined healthcare budgeting transforms unmanaged medical liabilities into controlled, predictable tax savings.
Read more: Understanding the Reality of Health Insurance Denial and Fighting Back
Actionable Tactical Steps to Avoid Hidden Billing Traps and Reduce Expenses
Open Enrollment Audit Tactics and Provider Network Audits
Active annual plan evaluation prevents passive policy auto-enrollment from quietly increasing your monthly health insurance cost rates. Insurance carriers regularly update rate schedules, provider directories, and medication formularies between policy years. Spending time during open enrollment to re-evaluate regional carriers ensures you do not remain locked into an outdated, overpriced plan structure.
Executing a thorough provider network check is essential before committing to any prospective plan option. Contact primary care physicians and specialist offices directly to verify active participation in specific Marketplace network tiers for the upcoming year. Relying solely on outdated online directories can lead to accidental out-of-network visits that dramatically elevate personal healthcare liabilities.
Medical Bill Negotiation Strategies and Appeals Protocols
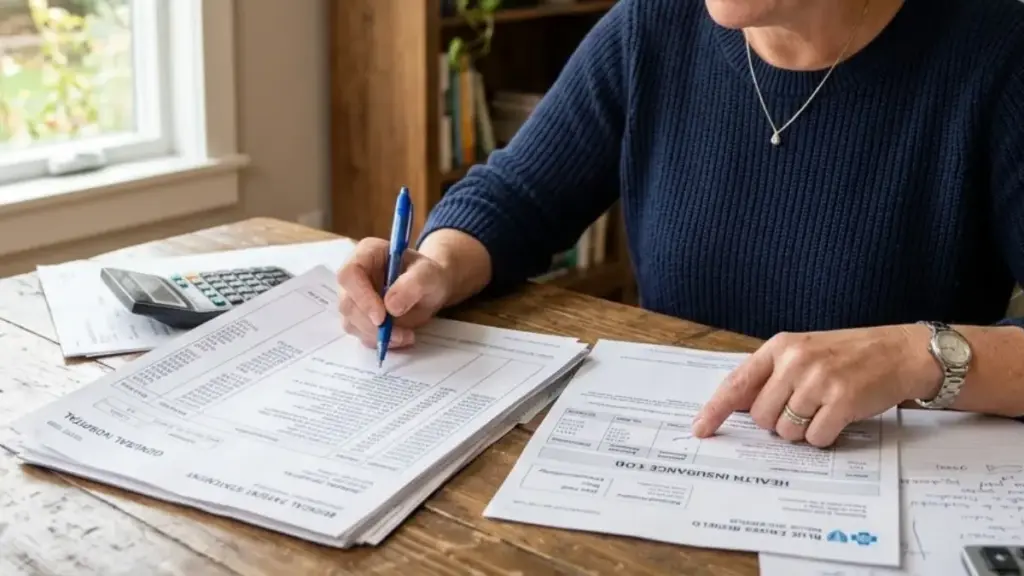
Requesting fully itemized billing statements for hospital visits is a critical tactic for managing your total health insurance cost output. Medical billing departments frequently make administrative coding errors, charge for unrendered treatments, or double-bill for routine medical supplies. Auditing each line item against your explanation of benefits (EOB) sheet reveals discrepancies that can be disputed and erased from your balance statement.
When insurance carriers issue formal claim denials, leveraging the official appeals process offers a reliable pathway to reverse improper charges. Work closely with healthcare providers to assemble comprehensive medical necessity documentation, supporting peer-reviewed evidence, and detailed physician letters. Persistent administrative appeals routinely overturn initial claim rejections, saving policyholders thousands of dollars in unnecessary out-of-pocket medical debt.
Frequently Asked Questions About Health Insurance Cost Management
Why did my monthly premium increase even though my health status remained unchanged?
General medical service inflation, insurer network recalibrations, and rising prescription drug costs force carriers to raise baseline rates across entire risk pools regardless of individual health status.
How do I verify my eligibility for ACA Premium Tax Credit discounts?
Eligibility depends on your estimated household modified adjusted gross income (MAGI) relative to federal poverty guidelines, family size, and local baseline plan costs available on the official Marketplace portal.
What steps should I take if I receive a surprise out-of-network emergency bill?
Leverage federal protections under the No Surprises Act, request an itemized billing invoice, notify your insurer immediately, and file a formal dispute if emergency facility fees exceed standard in-network cost-sharing limits.
Securing Long-Term Financial Stability Against Rising Health Insurance Cost Trends
Proactive healthcare planning remains your strongest defense against unpredictable premium spikes and hidden industry fee structures. By thoroughly auditing policy fine print, accurately adjusting income projections for tax credits, and utilizing tax-exempt savings vessels, consumers can successfully insulate their household budgets from sudden medical inflation. Taking charge of your insurance coverage transforms a complex financial burden into a manageable, predictable household expense.
Continuous vigilance during annual open enrollment periods ensures your coverage continuously adapts to evolving family needs and economic conditions. Do not allow insurance carriers to dictate your financial security through passive auto-renewals and hidden fee increases. Educate yourself on network limits, audit itemized billings, and utilize every available legislative protection to maintain optimal healthcare coverage at a fair, predictable cost.
PLEASE LEAVE A COMMENT TO SHARE YOUR FAVORITE THOUGHTS OR FOLLOW OUR BLOG FOR THE LATEST UPDATES.
Leave a Reply